Blog

  • Perimenopause at Work: Career, Health & Financial Strategy

    Perimenopause at Work: Career, Health & Financial Strategy


    Professional woman in her 40s working at a laptop in a modern office, representing perimenopause workplace strategies

    For decades, conversations about career growth and women’s health ran on parallel tracks. That separation is no longer sustainable. As more women occupy leadership roles, executive positions, and entrepreneurial ventures, the mid-career transition known as perimenopause has become impossible to ignore.

    In the United States, perimenopause—the years of hormonal fluctuation leading up to menopause—most often begins between ages 35 and 55. This window overlaps almost exactly with the period of peak earning power, maximum career responsibility, and highest potential for advancement. The result is a collision of biology and professional demand that many women experience as a sudden, unexplained decline in focus, energy, and resilience.

    Generic wellness advice is not enough. What is required is a deliberate strategy that protects cognitive performance, leverages available legal and workplace protections, and safeguards long-term financial security. This guide provides that framework: practical adjustments you can implement immediately, clear language for conversations with managers and HR, and financial considerations that protect your future self.


    1. The Biological & Workplace Reality of Perimenopause

    Perimenopause is defined by irregular fluctuations—and eventual decline—in estrogen and progesterone. While hot flashes and night sweats receive the most public attention, the less visible effects on the brain and nervous system often create the greatest workplace friction.

    Cognitive Effects and “Brain Fog”

    Estrogen influences neurotransmitter activity, glucose metabolism in the brain, and the efficiency of neural signaling. When levels fluctuate, many women experience temporary difficulties with verbal recall, concentration, working memory, and the ability to switch between tasks. According to guidance from Harvard Health Publishing, these changes are real physiological responses rather than simple stress or aging.

    In professional settings this can surface as needing extra time to prepare for presentations, losing a train of thought mid-meeting, or feeling less sharp during complex problem-solving. These symptoms are often intermittent, which makes them particularly frustrating and easy to dismiss as personal failings.

    Sleep Architecture and Daytime Energy

    Night sweats, temperature dysregulation, and shifts in circadian rhythm frequently fragment deep and REM sleep. The U.S. Office on Women’s Health notes that chronic sleep disruption directly impairs executive function, emotional regulation, and stress tolerance the following day. Over time, this creates a compounding cycle: poor sleep worsens cognitive symptoms, which increases perceived workload stress, which further disrupts sleep.

    The Misdiagnosis Challenge

    Symptoms of perimenopause frequently overlap with those of high workplace stress, anxiety, depression, or thyroid dysfunction. Clinical resources from the Mayo Clinic emphasize that delayed recognition is common. Women may spend months or years treating secondary issues while the underlying hormonal transition continues unaddressed. Early consultation with a clinician knowledgeable about midlife hormonal health can shorten this cycle and open the door to targeted treatment options, including lifestyle interventions and, when appropriate, hormone therapy.

    “Navigating mid-career physical transitions is not a personal shortcoming—it is an executive logistics challenge. The goal is not to ‘power through’ but to redesign systems so that performance and well-being remain aligned.”

    2. Workplace Adjustments & Executive Productivity Strategies

    Protecting output during high-demand periods rarely requires working longer hours. It requires aligning the most cognitively demanding work with your highest-energy windows and reducing unnecessary friction the rest of the day.

    Workplace Challenge Biological Trigger Actionable Strategy
    Cognitive Fatigue / Brain Fog Fluctuating estrogen affecting brain glucose use and neural efficiency Protect morning hours for deep work; batch administrative tasks for lower-energy periods; use written notes and AI transcription tools to reduce reliance on working memory
    Thermal Discomfort Vasomotor instability (hot flashes) Request seating near ventilation or windows; keep a personal fan and cooling layer options; choose breathable fabrics and layered clothing
    Variable Daily Energy Sleep fragmentation and nighttime micro-awakenings Implement strict time-blocking; schedule high-stakes meetings earlier; protect short recovery breaks between intense sessions
    Stress Amplification Heightened cortisol sensitivity during hormonal transition Build mandatory 5–10 minute cognitive resets between back-to-back commitments; practice brief grounding or breathing techniques
    Verbal Recall Friction Temporary word-finding difficulty Prepare key talking points in advance; keep a short reference note visible during meetings; normalize “let me come back to that” language

    Flat lay view of an organized executive desk with a digital tablet displaying a daily schedule planner

    Time-Blocking for Maximum Output

    Most knowledge workers still organize their calendars around traditional business hours rather than biological energy. A more effective approach is to treat cognitive capacity as a limited resource that rises and falls across the day.

    • Reserve the first 2–3 high-focus hours after you arrive (or after your personal peak) for strategic work, writing, analysis, or decision-making.
    • Move routine email processing, status updates, and administrative tasks to mid- or late-afternoon when energy naturally dips.
    • Batch similar meetings together and insert short buffer blocks so you are not constantly context-switching.
    • Protect at least one 10–15 minute recovery window after intense sessions—walk, stretch, or simply step away from screens.

    Over several weeks this structure often produces higher-quality output with less total effort and reduced end-of-day depletion.

    Practical Daily Micro-Strategies

    • Keep a running external “brain dump” note (digital or paper) so open loops do not consume working memory.
    • Use templates and checklists for recurring processes to reduce decision fatigue.
    • When possible, request agendas in advance so you can prepare key points rather than relying on spontaneous recall.
    • Hydrate consistently and maintain protein-inclusive meals or snacks to stabilize blood sugar and energy.

    3. Navigating Legal Protections & HR Frameworks in the US

    Professional women in the United States have several potential avenues for support, though the legal landscape requires careful navigation. Perimenopause itself is not automatically classified as a disability, yet severe symptoms can still trigger protections.

    Reasonable Accommodations under the ADA

    The Americans with Disabilities Act applies when a physical or mental impairment substantially limits one or more major life activities (including sleeping, concentrating, thinking, or working). Severe hot flashes, debilitating fatigue, or significant cognitive disruption may meet this threshold in individual cases. The U.S. Equal Employment Opportunity Commission (EEOC) requires employers to engage in an interactive process to identify reasonable accommodations that do not create undue hardship. Examples include modified schedules, temperature adjustments, hybrid or remote work options, or temporary changes in job duties.

    Family and Medical Leave Act (FMLA)

    Under guidelines administered by the U.S. Department of Labor, eligible employees of covered employers may take up to 12 weeks of job-protected unpaid leave for a serious health condition. If perimenopause symptoms require ongoing treatment or prevent the employee from performing essential job functions, FMLA leave may be available—either continuously or intermittently.

    Pregnant Workers Fairness Act (PWFA) and Evolving Interpretations

    The PWFA requires reasonable accommodations for known limitations related to pregnancy, childbirth, or related medical conditions. EEOC regulations and subsequent guidance have treated menstruation-related conditions within this framework. Whether perimenopause and menopause fall under “related medical conditions” continues to be clarified through agency guidance and court decisions on a case-by-case basis. Some advocates and legal analyses argue for broader inclusion; employers and employees should monitor developments closely. In the meantime, many of the same practical accommodations can often be requested under the ADA or through informal workplace flexibility policies.

    State and local laws are also expanding. Several jurisdictions have begun or are considering explicit protections related to menopause symptoms. Checking both federal rights and applicable state rules is advisable.

    Practical next step: Document symptoms and their workplace impact (dates, frequency, functional limitations). When requesting accommodations, focus on specific, job-related adjustments rather than a broad diagnosis. HR and managers respond more effectively to concrete solutions.

    4. Safeguarding Financial Continuity & Long-Term Wealth

    The years between 40 and 55 are typically the highest-earning and highest-contribution period for retirement accounts. Interruptions during this window carry outsized long-term consequences.

    1. 401(k) and Retirement Compound Growth
      Peak contribution years plus employer matching form the foundation of most private retirement wealth. Reduced hours, lateral moves with lower pay, or temporary exits shrink both employee contributions and matching dollars. Because of compounding, even a two- or three-year reduction can translate into tens of thousands of dollars less at retirement.
    2. Social Security Benefit Calculations
      Benefits are based on the highest 35 years of indexed earnings. Years of zero or significantly reduced earnings pull the average downward. Leaving the workforce early or dropping to part-time status during peak years permanently lowers the eventual monthly benefit.
    3. Health Insurance Continuity
      Employer-sponsored group coverage remains one of the most cost-effective ways to access specialists, diagnostic testing, and potential hormone therapy. Losing coverage can mean higher premiums on the individual market, delayed care, or higher out-of-pocket costs precisely when medical support is most valuable.

    Before considering a full exit or major reduction in hours, evaluate intermediate options: temporary reduced travel, project-based or consulting arrangements, formal medical leave under FMLA, or negotiated flexibility that preserves full-time status and benefits.

    Financial Action Point: Run a simple scenario analysis with your financial planner or using free online retirement calculators. Compare the long-term impact of staying employed with modest accommodations versus a multi-year reduction in earnings. The numbers often clarify the value of staying engaged, even at a modified pace.

    5. Frequently Asked Questions (FAQ)

    Q: How does perimenopause impact career productivity?

    A: Fluctuating estrogen and progesterone commonly produce sleep disruption, daytime fatigue, brain fog, and reduced concentration. Studies indicate that perimenopausal women report higher levels of work impairment than women who have not yet entered or have completed the transition. The combination of cognitive friction and lower energy can affect meeting performance, written output, and the ability to sustain long days—particularly during the peak earning years of ages 35–55. Structured routines, energy-aligned scheduling, and symptom management significantly reduce these effects for most women.

    Q: Can I request workplace accommodations for perimenopause in the United States?

    A: Yes, under appropriate circumstances. The ADA may require reasonable accommodations when symptoms substantially limit major life activities such as sleeping, concentrating, or working. FMLA can provide job-protected leave if the condition meets the definition of a serious health condition. The PWFA and related guidance continue to evolve regarding menopause-related limitations. Many employers will also grant informal flexibility once the functional impact is clearly explained. Document symptoms and propose specific, low-cost adjustments (flexible hours, temperature control, hybrid work, etc.).

    Q: Does stepping out of the workforce early during perimenopause impact retirement?

    A: Significantly. Reduced or interrupted contributions during the highest-earning years diminish 401(k) balances and employer matches. Social Security calculations incorporate the highest 35 years of earnings; lower or zero-earning years reduce the average. Loss of employer-sponsored health coverage can also increase medical expenses. Even temporary career breaks compound over decades. Exploring flexible or leave options that preserve employment status and benefits is almost always preferable from a long-term wealth perspective.

    Q: What should I say when talking to my manager or HR?

    A: Focus on function rather than diagnosis. Example language: “I’ve been experiencing some temporary health-related changes that affect my energy and concentration at certain times of day. I’d like to discuss a few adjustments—such as protecting mornings for deep work and having more flexible start times—that would help me maintain strong performance.” Bring specific proposals and be prepared to engage in an interactive discussion.


    Conclusion & Strategic Next Steps

    Perimenopause is a predictable biological transition, not a career-ending event. Women who approach it with the same strategic mindset they apply to major projects—gathering accurate information, redesigning systems, advocating clearly, and protecting long-term resources—consistently maintain both performance and trajectory.

    Start with three concrete actions this week:

    1. Audit your current calendar against your actual energy patterns and begin time-blocking high-value work into peak windows.
    2. Review your employer’s health benefits, leave policies, and any existing flexibility options.
    3. Schedule a conversation with a healthcare provider experienced in midlife hormonal health to rule out overlapping conditions and explore evidence-based symptom support.

    With deliberate systems in place, the mid-career years can remain a period of continued growth, influence, and financial strengthening rather than a period of silent struggle.

    Disclaimer

    This article is for general informational and educational purposes only. It does not constitute medical, legal, or financial advice.

    The legal and workplace information refers primarily to United States federal laws (including the ADA, FMLA, and PWFA) as of the publication date. Employment laws vary by country and state, and interpretations can change. Readers outside the United States should consult local laws and qualified professionals in their jurisdiction.

    Perimenopause and menopause experiences differ widely. Always consult a qualified healthcare provider for personal medical advice, diagnosis, or treatment decisions. The author is not a licensed medical, legal, or financial professional in the United States or any other country.

  • Editorial Policy

    Last Updated: September 18, 2026

    WomenSteps is an independent digital publication providing practical, research-backed guidance on career growth, executive leadership, personal finance, and balanced lifestyle strategies for women navigating complex professional and personal milestones.

    Our editorial approach emphasizes analytical clarity, practical utility, verified primary sourcing, and complete transparency. We aim to convert complex industry, career, and financial subjects into actionable frameworks while clearly distinguishing factual reporting from editorial analysis and commentary.


    1. Editorial Ownership & Human Authorship

    WomenSteps is founded and directed by Richa M., MBA, an experienced business strategist and content director with over 15 years of organizational management and operational experience. All editorial strategies, topic selections, and published guides reflect hands-on human oversight.

    The site presents professional credentials accurately. WomenSteps and its editorial team do not hold licenses as United States medical doctors, certified public accountants (CPAs), certified financial planners (CFPs), licensed attorneys, or insurance brokers. Specialized topics are researched through authoritative third-party public records, and readers are consistently guided to consult licensed professionals for individualized decisions.


    2. Research Standards & Primary Sourcing

    To ensure high informational value and accuracy, our content is constructed from credible, publicly verifiable sources:

    • Government & Regulatory Agencies: For employment legislation, federal grant availability, statutory benefits, and national statistics, we cite direct primary sources (e.g., U.S. Department of Labor, IRS, SBA, CDC, and state administrative portals).
    • Academic & Institutional Research: We consult peer-reviewed journals, university research bureaus, and recognized industry bodies (such as corporate governance studies and leadership institutes).
    • Original Analysis & Frameworks: We synthesize complex source documents into proprietary step-by-step guides, comparative tables, checklists, and actionable execution roadmaps tailored to ambitious women.
    • Cross-Verification: When discrepancies occur across data points or surveys, we investigate jurisdiction-level differences, filing timelines, eligibility parameters, or legislative amendments before publishing.

    3. Geographic Scope (Targeted US Guidance)

    Many WomenSteps articles examine United States corporate practices, executive equity structures, federal regulations, state-specific guidelines, or educational curricula. These analyses are developed as thoroughly researched comparative education.

    Because statutory rules, financial thresholds, tax laws, and workplace mandates vary by state and local jurisdiction, readers must independently verify current legal statutes and administrative rules with the appropriate local government agency or institutional board.


    4. E-E-A-T Disclaimers & Niche Boundaries

    Career & Employment Analysis: Career playbooks, negotiation scripts, and executive frameworks are educational resources. State-level labor codes, non-compete enforceability, and corporate governance rules change frequently; our guides do not constitute legal counsel.

    Financial Literacy & Wealth Strategy: Discussions regarding corporate benefits, equity compensation, HSA accounts, retirement planning, and entrepreneurship grants are strictly educational. They do not constitute personalized financial planning, tax preparation, or securities advice.

    Wellness & Daily Lifestyle: Lifestyle and workplace wellness content focuses exclusively on preventative routines, sustainable habit formation, and stress management. Our articles do not provide medical diagnosis, clinical treatment protocols, or pharmaceutical recommendations.


    5. Responsible Use of Editorial Tools & AI

    Modern digital tools, including AI-assisted analytical software, may be utilized during preliminary research, structural brainstorming, outlining, or copy-editing workflows. However, technology never replaces our human editorial responsibility.

    Every article published on WomenSteps undergoes rigorous human review, source verification, line-editing, and factual validation by our editorial team. We strictly prohibit the publication of unedited, automated, or scraped content.


    6. Corrections, Updates & Content Maintenance

    We maintain our content archive through continuous auditing. Articles are systematically updated to incorporate revised statutory limits, refreshed market data, active application deadlines, and updated institutional citations.

    • An updated date reflects that the article has been evaluated as part of our regular editorial maintenance cycle.
    • If a reader identifies an out-of-date metric or a factual error, we encourage submitting an edit request via our contact channels with the page URL and supporting official source documentation. Verified errors are rectified promptly.

    7. Commercial Independence & Advertising Transparency

    WomenSteps maintains a strict separation between editorial content and commercial monetization:

    • Advertising: Third-party programmatic advertising, including Google AdSense, is rendered separately from editorial content. Advertisers have no voice in topic selection, data interpretations, or editorial conclusions.
    • Affiliate Partnerships: Certain articles may incorporate affiliate links for services, books, or executive tools. If a reader makes a purchase through an affiliate link, WomenSteps may receive compensation at zero extra cost to the buyer. We only reference resources that meet our editorial standards.

    8. Editorial Inquiries & Contact Information

    For factual corrections, press releases, editorial feedback, or syndicate requests, please connect directly with our editorial team:

  • ​Executive Equity Negotiation for Women: Benefits & Salary Guide

    ​Executive Equity Negotiation for Women: Benefits & Salary Guide


    Female corporate executive analyzing executive equity compensation agreement
    Maximizing long-term wealth accumulation through strategic equity and executive benefit negotiations.

    For high-performing corporate leaders, moving into senior director, VP, or C-suite positions marks a critical shift in wealth creation. Base salary alone rarely builds generation-defining financial security. Instead, true long-term net worth is forged through equity grants, performance stock units, and executive benefit protections.

    Despite making significant strides in corporate leadership, female executives often encounter equity compensation gaps during offer discussions. Negotiating a compensation package requires mastering equity vehicles, vesting acceleration mechanics, tax strategies, and protective exit terms before signing an offer letter.


    1. Understanding the Executive Equity Mix

    Before negotiating grant sizes, it is vital to understand the primary structures used by private startups and publicly traded corporations across the United States.

    Equity Structure Primary Feature Key Tax & Vesting Considerations
    Restricted Stock Units (RSUs) Direct shares granted upon satisfying a vesting schedule. Taxed as ordinary income at vesting; subject to federal income guidelines via the Internal Revenue Service (IRS).
    Incentive Stock Options (ISOs) Right to purchase stock at a fixed strike price with tax benefits. Qualifies for long-term capital gains if holding periods are met; may trigger Alternative Minimum Tax (AMT).
    Non-Qualified Options (NSOs) Flexible stock options available to board members and executives. Taxed as ordinary income on the spread value between exercise price and fair market value at exercise.
    Performance Stock Units (PSUs) Equity tied directly to corporate financial targets (e.g., EBITDA). Requires clear KPI definitions to ensure performance metrics are realistically attainable.

    Vesting Schedules and Clifftops

    The industry standard in tech and corporate sectors remains a 4-year vesting schedule with a 1-year cliff (25% vests after 12 months, followed by monthly or quarterly vesting). When entering an established firm at an executive level, negotiate for a reduced cliff or immediate monthly vesting credit if you are forfeiting unvested equity at your current employer.


    2. Protecting Your Grant: Double-Trigger Acceleration & Dilution Clauses

    Private enterprise growth, private equity buyouts, and corporate mergers introduce volatility. Securing strategic equity clauses protects your financial upside during corporate restructuring.

    • Single-Trigger vs. Double-Trigger Acceleration: Single-trigger accelerates equity vesting immediately upon a company acquisition. Double-trigger requires both an acquisition AND a termination without cause (or constructive dismissal) within 12 months. Employers favor double-trigger clauses; ensure yours is explicitly written into your equity grant agreement.
    • Anti-Dilution Protections: In early-to-mid stage startups, subsequent fundraising rounds can dilute your ownership percentage. Review structural terms with legal counsel licensed by the American Bar Association (ABA) to negotiate secondary anti-dilution provisions or top-up grant rights.
    • Extended Exercise Windows: Standard post-termination option exercise windows are typically 90 days. Negotiate an extended exercise window (e.g., 2 to 7 years) if leaving on good terms, preventing cash-flow strain when exercising stock options.
    “Equity without acceleration and exit protections is merely conditional paper wealth. Negotiating protective provisions on Day 1 ensures your financial interests remain secure throughout corporate transitions.”

    Executive contract documents detailing stock options, RSUs, and benefits packages
    Documenting legal terms, vesting schedules, and executive severance protections early ensures long-term security.


    3. Negotiating High-Value Non-Salary Executive Benefits

    Base salary cap constraints often exist due to internal band structures. However, non-salary executive benefits offer immense room for customization.

    1. Severance Protection (“Golden Parachutes”): Ensure your contract guarantees 6 to 12 months of continued base salary, prorated annual bonus payout, and COBRA health coverage continuation if terminated without cause.
    2. Legal Fee Reimbursement: Custom executive offer contracts require attorney reviews. Request an upfront legal fee allowance ($3,000 to $7,500) covered by the hiring company.
    3. Executive Health & Wellness Perks: Negotiate comprehensive executive health physicals, dedicated coaching stipends, and flexible travel parameters (such as business class upgrades for long-haul international flights).
    4. 401(k) Non-Qualified Deferred Compensation (NQDC): For high earners hitting traditional 401(k) contribution caps defined by federal tax policies, request access to NQDC plans to defer pre-tax income into long-term investment vehicles.

    4. Frequently Asked Questions (FAQ)

    Q: What is the difference between ISOs and NSOs in executive equity compensation?

    A: Incentive Stock Options (ISOs) offer favorable tax treatment under federal guidelines by allowing capital gains rates if holding rules are met, though they may trigger Alternative Minimum Tax (AMT). Non-Qualified Stock Options (NSOs) do not qualify for special tax treatment and are taxed as ordinary income upon exercise on the spread value.

    Q: How should women negotiate double-trigger acceleration clauses in equity grants?

    A: Explicitly request double-trigger acceleration terms in your executive employment agreement. This guarantees that if the company undergoes a change of control and your employment is terminated or modified substantially within 12 months, all unvested stock options or RSUs immediately vest.

    Q: Can non-salary executive benefits like severance and health coverage be negotiated upfront?

    A: Yes. Executive severance terms (e.g., 6–12 months pay), legal review stipends, COBRA continuation, and executive physicals are standard negotiation points that provide substantial value beyond base salary.


    Conclusion & Strategic Execution

    Negotiating an executive package requires balancing immediate cash flow with equity upside and structural legal protections. Treat equity discussions as a strategic partnership conversation, demonstrating your understanding of company valuation, long-term performance growth, and corporate governance.

    Review your proposed offer letter with a specialized executive employment attorney, evaluate your equity tax implications with a CPA, and secure terms that reflect the value you bring to the board and executive team.

  • Best Life Insurance for Women in 2026: Cost & Coverage Guide

    Best Life Insurance for Women in 2026: Cost & Coverage Guide


    Life Insurance Guide for Women in the US
    Understanding financial protection and tailored life insurance policy strategies for women.

    Navigating the financial landscape in the United States requires tailored strategies, especially when securing a family’s long-term financial future. Historically, life insurance planning centered primarily on traditional male wage earners. However, as American women increasingly take on roles as primary breadwinners, corporate executives, entrepreneurs, co-heads of household, and essential caregivers, life insurance has become a non-negotiable cornerstone of household solvency and wealth preservation.

    Whether you are a professional operating in major metropolitan hubs, a self-employed business owner in growing suburban markets, or a full-time stay-at-home mother managing family logistics, selecting the correct coverage requires understanding mortality tables, medical underwriting metrics, state regulations, and living benefit riders. This comprehensive guide breaks down the precise mechanics of life insurance for women across every major life stage.


    1. Why Life Insurance Pricing and Underwriting Differ for Women

    From an actuarial perspective, life insurance companies evaluate risk based on statistical longevity, biological risk indicators, and occupational hazards. In the United States, female applicants systematically enjoy an advantage in baseline pricing structures.

    • Longer Biological Life Expectancy: According to long-term demographic research published by the CDC National Center for Health Statistics, women in the United States outlive men by roughly 5 years on average. Because life insurance carriers expect to collect monthly premiums over a longer time horizon before paying out a death benefit, baseline policy rates for women are frequently 20% to 30% lower than those for men of identical age and health profiles.
    • The Economic Value of Unpaid Caregiving: A widespread mistake made by American households is underinsuring non-working mothers. The US Bureau of Labor Statistics (BLS) continuously tracks domestic and eldercare contributions. If a primary caregiving parent passes away unexpectedly, the surviving spouse must pay out-of-pocket for childcare, transportation, housekeeping, and eldercare—costs that easily exceed $100,000 annually in major metropolitan markets.
    • Rising Female Entrepreneurship: Over 13 million businesses in the US are now female-owned. Women entrepreneurs borrowing for expansion often require life insurance collateral assignments to satisfy loan requirements set by the US Small Business Administration (SBA) while protecting business continuity through buy-sell agreements.
    “Life insurance isn’t just a replacement for cash income; it is a financial buffer that preserves household stability, covers domestic labor replacement, and safeguards long-term generational wealth.”

    2. In-Depth Breakdown of Policy Options

    Choosing between temporary and permanent life insurance depends heavily on your immediate cash flow, long-term wealth transfer plans, and primary family obligations. The National Association of Insurance Commissioners (NAIC) outlines two core policy paths: term protection and permanent cash-value structures.

    Insurance Type Coverage Duration Avg. Monthly Premium (US Range) Ideal Strategy
    Term Life Insurance 10 to 30 Years $18 – $45 / month Income replacement during child-rearing years & mortgage payoff.
    Whole Life Insurance Lifetime (Permanent) $150 – $350+ / month Guaranteed legacy transfer, cash value accumulation, & estate taxes.
    Universal Life (UL / INDEXED) Flexible / Lifetime $100 – $250 / month Tax-deferred growth potential tied to financial indices like the S&P 500.
    Final Expense (Graded) Lifetime $40 – $90 / month Seniors seeking basic funeral, burial, and end-of-life medical coverage.

    Term Life Insurance: The Budget-Friendly Workhorse

    Term life insurance remains the most straightforward and cost-effective insurance vehicle in the American marketplace. You select a fixed duration—typically 10, 15, 20, or 30 years—and a death benefit amount (e.g., $500,000 or $1,000,000). If you pass away during this designated term, your beneficiaries receive the full tax-free death benefit payout.

    For young families, a 20-year or 30-year term policy guarantees that mortgage obligations, debt payoffs, and higher education tuition costs remain protected while children grow to independence.

    Permanent Life Insurance: Estate Planning & Cash Value

    Unlike term policies, permanent options (Whole Life, Universal Life, and Variable Universal Life) stay active for your entire lifespan, provided required premiums are paid. A portion of every premium payment accumulates within a tax-deferred cash value account that grows over time.

    High-earning executives and business founders frequently utilize permanent policies to build liquid assets that can be borrowed against tax-free during retirement or structured to offset federal and state estate tax liabilities upon wealth transfer.


    3. Life Insurance Planning by Age Bracket

    Your financial goals and health profile evolve significantly over time. Here is how women should approach life insurance planning across different decades:


    Life Insurance Options Across Age Brackets
    Financial objectives and coverage requirements transition across key life stages.

    In Your 20s: Lock in Lowest Rates & Protect Student Loans

    In your 20s, health risks are statistically low, making premiums cheaper than at any other period in adulthood. If you have co-signed private student loan debt, securing a modest 20-year term policy ensures your co-signers (such as parents) are not burdened with debt if the unexpected happens.

    In Your 30s: Income Replacement & Family Protection

    The 30s are prime years for marriage, home purchases, and raising young children. The primary goal during this phase is replacing income and funding domestic stability. Stacking term policies (e.g., a 30-year policy for mortgage protection combined with a 10-year policy for high-cost early childcare years) is a cost-effective strategy used by financial planners.

    In Your 40s: Pre-Retirement Cushion & Critical Illness Focus

    By your 40s, health considerations become more prominent in underwriting evaluations. Securing coverage before common mid-life health diagnoses occur is vital. Adding living benefit riders (such as critical illness and chronic care riders) guarantees financial assistance if medical emergencies strike during peak earning years.

    In Your 50s and Beyond: Estate Liquidity & Final Expenses

    As children reach independence and mortgages near payoff, priorities shift toward legacy transfer, tax optimization, and covering funeral or end-of-life medical expenses. Guaranteed acceptance policies or conversion options on existing term plans become invaluable assets during this decade.


    4. Critical Illness & Living Benefits: Essential Protection for Women

    A standard death benefit pays out exclusively upon death. Modern US insurance products offer optional extensions known as Living Benefit Riders or standalone Critical Illness Coverage. These mechanisms allow policyholders to access a major portion of their policy payout while still alive if diagnosed with qualifying medical conditions.

    According to epidemiological studies from the American Cancer Society, approximately 1 in 8 women in the United States will develop invasive breast cancer in their lifetime. Cardiovascular disease also remains a leading health challenge for adult women across the nation.

    How Critical Illness Riders Work

    If you experience a major medical diagnosis—such as invasive breast cancer, stroke, major organ failure, or a sudden heart attack—your policy pays out a tax-free lump sum directly to you. You maintain total freedom over how these funds are allocated, including:

    • Covering high health insurance deductibles, co-insurance, and out-of-pocket maximums.
    • Funding experimental treatments or consulting out-of-network medical specialists (e.g., major academic medical centers).
    • Maintaining monthly mortgage, car, and essential utility payments while taking unpaid leave under the federal Family and Medical Leave Act (FMLA).
    • Replacing lost business revenues or paying key staff during recovery.

    5. Calculating Required Coverage: The DIME Framework

    Determining how much coverage to secure depends on your unique household income, outstanding debts, and long-term financial goals. Financial planners rely heavily on the DIME Method for accurate calculations:

    1. D – Debt: Sum up all non-mortgage liabilities, including personal loans, credit card balances, auto financing, and student debt.
    2. I – Income: Multiply your annual salary or income by the number of years your family needs support until dependents reach independence (e.g., $80,000 x 15 years = $1,200,000).
    3. M – Mortgage: Calculate the exact principal balance required to fully clear your primary home loan.
    4. E – Education: Estimate higher education expenses for dependents. Average costs for 4-year public US universities currently range between $100,000 and $250,000 per child (including room and board).
    Sample Household Formula: A mother earning $85,000 annually with $20,000 in auto loans, a $280,000 home mortgage, and two young children planning for higher education would calculate:
    $20,000 (Debt) + $850,000 (10 yrs Income) + $280,000 (Mortgage) + $200,000 (Education) = $1,350,000 Total Policy Target.

    6. Navigating US State Regulations and Underwriting Steps

    Insurance regulations across the United States are governed at the state level by State Insurance Commissioners rather than a single federal agency. You can review consumer protection guidelines through your local state department via the NAIC State Insurance Directory.

    Key Regulatory Rights to Keep in Mind

    • The Free Look Period: Most US states require insurance companies to offer a 10 to 30 day “Free Look” period. If you purchase a policy and decide to cancel it within this window, you receive a full refund of all premiums paid.
    • Grace Periods: By law, insurers must offer a grace period (typically 30 to 31 days) for missed premium payments before a policy lapses.
    • The Two-Year Contestability Period: During the first two years of a policy, carriers have the right to review claims for misrepresentations made on the original application. After two years, policies become incontestable except in cases of explicit fraud.

    Accelerated Underwriting vs. Paramedical Exams

    Modern insurance carriers utilize automated data tools—including prescription database checks, Motor Vehicle Reports (MVR), and credit-based insurance scores—to approve healthy applicants up to $2,000,000 in coverage without requiring physical blood or urine tests. If accelerated underwriting is not available due to medical history, a simple home paramedical exam will be scheduled at no cost to you.


    7. Frequently Asked Questions (FAQ)

    Q: Do women pay less for life insurance than men in the United States?

    A: Yes. Statistically, women in the US have a longer life expectancy than men (roughly 81 years compared to 76 years according to CDC demographic data). Because life insurance risk models evaluate mortality rates, female applicants generally receive lower monthly premiums across term and whole life policies.

    Q: How much life insurance coverage does a stay-at-home mother need?

    A: A stay-at-home mother provides crucial domestic and childcare services that would cost an estimated $100,000+ per year to replace through professional third-party services in the US. Financial planners generally recommend coverage between $250,000 and $500,000 for non-working parents.

    Q: Is critical illness insurance necessary alongside life insurance?

    A: A critical illness rider or standalone policy provides a tax-free lump-sum cash payout directly upon diagnosis of conditions like invasive breast cancer, stroke, or heart attack. It helps cover high health insurance deductibles, out-of-network specialists, and household bills during treatment.

    Q: Can I get life insurance while pregnant?

    A: Yes. Pregnancy does not prevent you from obtaining life insurance. However, applying during the first trimester or early second trimester is ideal before common pregnancy-related complications like gestational diabetes or elevated blood pressure occur, which could temporarily impact underwriting rates.


    Conclusion & Action Plan

    Securing an appropriate life insurance policy is one of the most effective actions an American woman can take to preserve family security, safeguard business investments, and protect long-term financial independence. By selecting a policy structure matched to your exact stage in life and taking advantage of modern living benefit riders, you build a resilient safety net for the future.

    To begin, assess your current liabilities using the DIME formula, gather quotes from top-tier US carriers, and consult an independent broker to lock in healthy rates today.

  • High-Yield Wealth Management & Tax Planning for C-Suite Women Executives


    For high-earning female C-suite executives—including CFOs, CROs, CMOs, and Chief Legal Officers—rapid compensation growth fundamentally alters wealth strategy. The focus shifts from basic wealth accumulation to tax mitigation, concentrated equity unwinding, IRC compliance, and high-yield preservation. Without deliberate financial engineering, modern executive compensation packages—composed of base salary, RSUs, stock options, performance units (PSUs), and deferred bonuses—frequently push marginal tax rates past 40% while creating dangerous single-stock portfolio exposure.

    Navigating modern corporate leadership requires proactive wealth modeling. By leveraging compliant Non-Qualified Deferred Compensation (NQDC) structures, optimizing Incentive Stock Option (ISO) exercise schedules to manage Alternative Minimum Tax (AMT) exposure, utilizing Section 721 exchange mechanisms, and deploying advanced estate trusts, executive women convert corporate compensation into multi-generational independence.


    High-Yield Wealth Management & Tax Planning for C-Suite Women Executives
    Figure 1: Strategic executive tax modeling coordinates equity exercise windows with tax-deferred compensation structures.

    1. Advanced Executive Equity Tax Optimization: ISOs, NQSOs, RSUs, and 83(b) Elections

    Managing executive equity demands a clear breakdown of tax trigger events and statutory holding periods. Improperly timed equity exercises can create massive phantom tax liabilities or forfeit long-term capital gains status.

    Equity Type Taxable Trigger Event IRS Classification Strategic Execution Protocol
    Restricted Stock Units (RSUs) Vesting Date Ordinary Income on full Fair Market Value (FMV) Execute automatic sell-to-cover for taxes; systematically rebalance post-vesting proceeds into diversified index funds or private credit.
    Incentive Stock Options (ISOs) Exercise Date (AMT) & Final Sale Date Spread = AMTI Preference Item; Qualified Sale = Long-Term Capital Gains Exercise early in the calendar year (January/February) to allow time to execute a disqualifying disposition if stock price drops before Dec 31.
    Non-Qualified Stock Options (NQSOs) Exercise Date Ordinary Income on spread (FMV minus Strike Price) + FICA taxes Delay exercise until near expiration to maximize time-value leveraging, unless paired with high-income gap year strategies.
    Restricted Stock Awards (RSAs) Grant Date (if 83b filed) or Vesting Date Ordinary Income on Grant Value $rightarrow$ Capital Gains on future growth File IRS Section 83(b) election within strict 30-day window post-grant to lock in baseline valuation for high-growth early-stage equity.

    The Mechanics of ISO AMT Calculations

    Incentive Stock Options provide substantial tax advantages, but exercising them without modeling the Alternative Minimum Tax can create severe tax shocks. The AMT spread calculation is governed by standard valuation principles:

    $$text{AMT Spread Preference} = (text{Fair Market Value at Exercise} – text{Strike Price}) times text{Number of Shares Executed}$$

    If the executive retains the stock through December 31, this phantom spread is added to Alternative Minimum Taxable Income (AMTI). To avoid paying cash tax on unliquidated paper gains, female executives should run quarterly AMT threshold modeling prior to executing large ISO blocks.

    2. Non-Qualified Deferred Compensation (NQDC) under IRC Section 409A

    Non-Qualified Deferred Compensation (NQDC) plans allow C-suite executives to defer up to 50% of base salary and up to 100% of executive annual bonuses. Because these plans bypass statutory 401(k) contribution caps ($23,500 standard limit), they serve as an effective tax shelter during peak earning years.


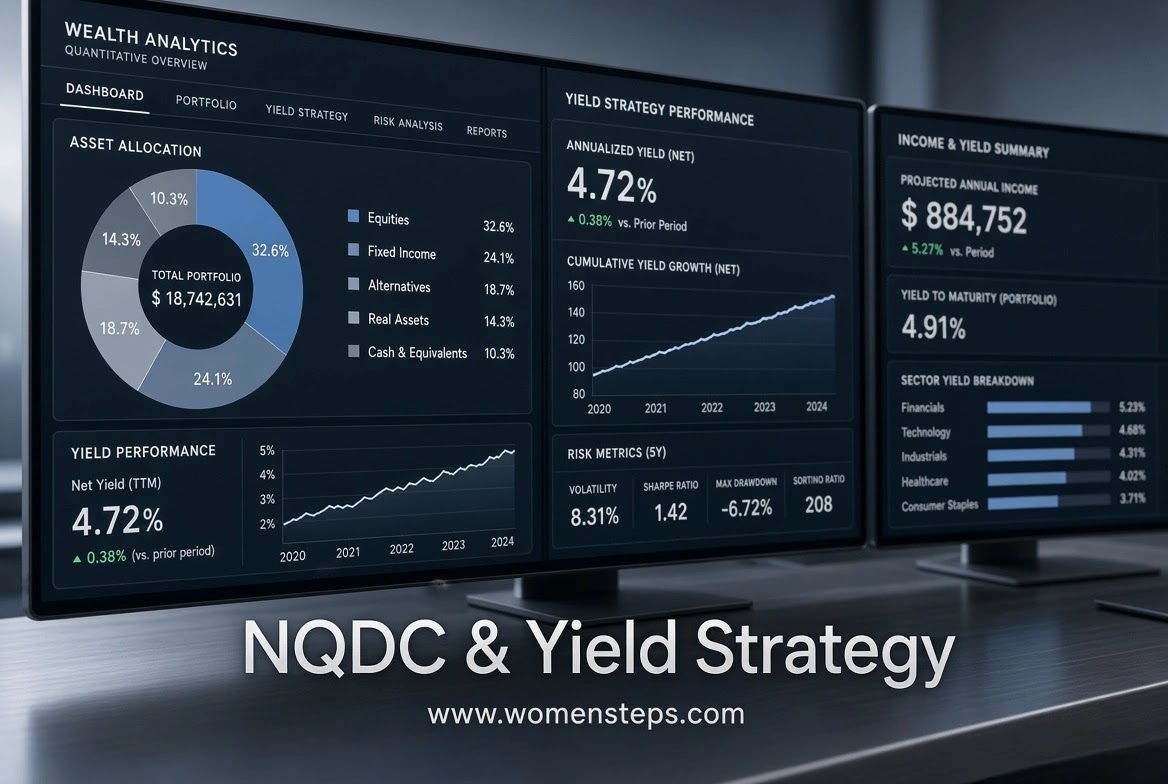
    NQDC & Yield Strategy - Quantitative Overview and Asset Allocation
    Figure 2: Structuring NQDC distributions across multi-year tranches flattens marginal tax curves during executive transition phases.

    Key Section 409A Regulatory Rules

    • Irrevocable Deferral Timing: IRS Section 409A requires that deferral elections be executed before the tax year in which the services are performed (e.g., electing by Dec 31, 2026 for bonus income earned in calendar year 2027).
    • Strict Payout Triggers: Distributions can only occur upon predefined events: retirement, separation from service, disability, death, change in corporate control, or an scheduled fixed calendar date.
    • Substantial Penalty Risk: Any non-compliant acceleration or delay of NQDC distributions triggers an automatic **20% federal penalty tax**, mandatory immediate income recognition, and penalty interest charges.
    • Credit Risk Protection via Rabbi Trusts: Because deferred NQDC assets legally remain general corporate assets subject to company creditors, demand that corporate deferred compensation balances be held inside an irrevocably funded **Rabbi Trust** to safeguard against corporate acquisition or management shifts.

    3. Concentrated Stock Unwinding & Tax-Free Diversification

    High-ranking female executives often accumulate over 60% of their net worth in their employer’s single stock. Holding concentrated positions creates immense personal balance sheet volatility. Executive financial planning utilizes four primary unwinding strategies:

    A. SEC Rule 10b5-1 Trading Plans

    Establish pre-scheduled, algorithmically driven sales schedules. Rule 10b5-1 plans provide affirmative defense against insider trading allegations while executing disciplined, dollar-cost-averaged stock liquidations across closed corporate trading windows. Ensure plans incorporate a mandatory 90-day cooling-off period required under updated SEC regulations.

    B. IRC Section 721 Private Exchange Funds

    Executives holding highly appreciated stock with negligible cost basis can contribute shares into a Section 721 Exchange Fund. The executive pool their stock with other concentrated stock owners, instantly receiving a diversified basket of multi-sector equities without triggering immediate capital gains realization under current tax law.

    C. Equity Options Hedging (Zero-Cost Collars)

    Protect equity downside without outright liquidation by purchasing an out-of-the-money put option financed simultaneously by selling an out-of-the-money call option. A zero-cost collar locks in a tight valuation band for concentrated stock positions while satisfying institutional holding obligations.

    D. Charitable Donor-Advised Funds (DAFs) & CRTs

    Transfer highly appreciated vested equity directly into a Donor-Advised Fund (DAF) or Charitable Remainder Unitrust (CRUT). Executives claim an immediate tax deduction equal to the stock’s full fair market value (up to 30% of AGI) while eliminating 100% of the embedded capital gains tax liability upon subsequent liquidation.


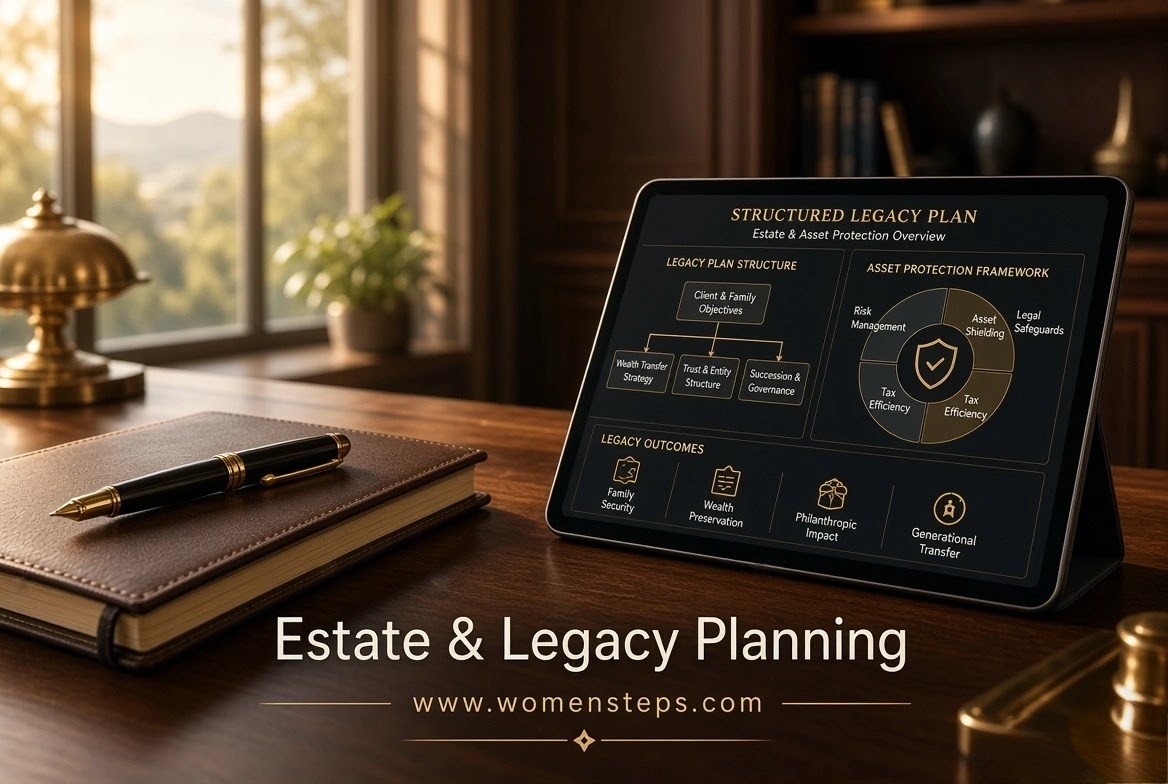
    Estate & Legacy Planning - Structured Legacy Plan Overview
    Figure 3: Multi-generational asset protection framework integrating trust governance and asset shielding.

    4. Executive Asset Protection & Multi-Generational Estate Engineering

    High-yield wealth management extends beyond liquid portfolio growth to protecting executive assets from corporate litigation liabilities and estate compression.

    C-Suite Estate & Asset Protection Protocol

    1. Spousal Lifetime Access Trusts (SLATs): Transfer high-growth assets into an irrevocable trust for the benefit of your spouse. SLATs remove appreciating assets from your taxable estate while preserving indirect access to trust income streams.
    2. Grantor Retained Annuity Trusts (GRATs): Transfer rapidly appreciating equity (e.g., pre-IPO stock or high-yield growth instruments) into a zeroed-out GRAT. Appreciated capital above the IRS Hurdle Rate (Section 7520) passes to beneficiaries completely free of gift tax.
    3. Private Placement Life Insurance (PPLI): Position high-yield alternative investments, private equity, and hedge fund allocations inside a variable PPLI structure to allow investment returns to compound 100% tax-free under IRC Section 7702.
    4. Corporate Umbrella Protection: Layer personal excess liability coverage (minimum $10M–$25M umbrella limit) directly over personal assets to insulate wealth from executive-level operational exposures.

    5. Related Strategic Leadership Guides

    Expand your knowledge base with complementary guides in our C-Suite Leadership series:

    6. Frequently Asked Questions

    How does IRC Section 409A impact Non-Qualified Deferred Compensation (NQDC)?

    IRC Section 409A dictates strict election and distribution timing rules for NQDC plans. Deferral elections must generally be made in the tax year prior to earning the income, and distributions can only be triggered by specific events (e.g., separation from service, disability, death, or fixed dates). Non-compliance results in an immediate 20% federal penalty tax plus premium interest charges.

    How is the Alternative Minimum Tax (AMT) triggered when exercising ISOs?

    When exercising Incentive Stock Options (ISOs) and holding the underlying shares beyond the calendar year end, the ‘spread’ (Fair Market Value minus Strike Price) is treated as an Alternative Minimum Taxable Income (AMTI) preference item, potentially triggering AMT even if no actual cash realized from a stock sale.

    What is an IRC Section 721 Exchange Fund and how does it benefit concentrated stock owners?

    An IRC Section 721 Exchange Fund allows qualified purchasers to contribute highly appreciated single-stock positions into a private partnership basket in exchange for a pro-rata share of the diversified portfolio, deferring capital gains tax realization until the fund interest is eventually liquidated.

    Why should high-earning women leaders consider an 83(b) Election for unvested equity?

    Filing an 83(b) election with the IRS within 30 days of receiving restricted stock allows executives to pay ordinary income tax on the equity’s current fair market value at grant, capping future growth taxation at favorable long-term capital gains rates upon eventual sale.

    Conclusion: Structuring Multi-Generational Financial Independence

    High-yield wealth management for C-suite women is about converting corporate earning power into institutional asset autonomy. By aligning equity exercise schedules, enforcing Section 409A deferred compensation compliance, systematically unwinding concentrated stock positions, and establishing tax-efficient estate trusts, female executives insulate their wealth against unnecessary tax friction and corporate risk.

    As C-suite compensation continues to evolve, women leaders who master advanced tax engineering ensure their capital remains protected, liquid, and positioned for sustainable multi-generational growth.

  • Enterprise Risk Management Frameworks for Female Chief Risk Officers (CROs)


    As global financial markets, regulatory mandates, and technological shifts increase enterprise complexity, the role of executive risk management has expanded from tactical compliance to core strategic execution. For female corporate leaders stepping into Chief Risk Officer (CRO) positions or serving on board risk committees, deploying robust enterprise risk management (ERM) frameworks is vital to safeguarding corporate assets while enabling bold value creation.

    Modern risk governance requires balancing downside threat mitigation with strategic opportunity capture. Regulatory guidance emphasized by global oversight bodies like the Basel Committee on Banking Supervision (BCBS) underscores that enterprise resilience depends on structural accountability and data-driven risk appetite modeling. This comprehensive guide analyzes global ERM standards, offering tactical playbooks for executive risk leaders to establish risk appetite metrics, structure three-lines governance, and present quantitative risk reporting directly to the board.


    Female Chief Risk Officer presenting quantitative risk dashboard to corporate board
    Figure 1: Strategic Enterprise Risk Management embeds quantitative risk metrics directly into C-suite decision-making.

    1. Standardizing Global ERM Frameworks: COSO vs. ISO 31000

    Selecting the optimal enterprise framework determines how seamlessly risk architecture integrates into corporate strategy. Executive risk leaders must evaluate structural methodologies based on industry regulatory scrutiny, operational scale, and governance maturity.

    Framework Standard Primary Core Focus Governance Architecture Ideal Enterprise Implementation
    COSO ERM Framework Strategy integration & internal financial controls 5 Interrelated Components / 20 Principles Public companies, SEC-regulated, financial institutions
    ISO 31000 Standard Flexible risk management principles & process Iterative 6-step risk treatment cycle Multinational tech enterprises & agile scale-ups
    Hybrid ERM Architecture COSO governance paired with ISO operational metrics Customized enterprise risk taxonomy Diversified holding companies & global conglomerates

    2. Operationalizing the Three Lines Governance Model

    A resilient risk governance model relies on clear operational boundaries. The updated Three Lines Model structured by the Institute of Internal Auditors (IIA) provides the foundational blueprint for executive accountability across operational and oversight roles.

    A. First-Line Operational Ownership

    Business unit managers and operational leaders serve as the first line of defense. They directly own, identify, and mitigate day-to-day operational risks within established business processes. Female CROs ensure business unit leaders are equipped with automated key risk indicators (KRIs) to monitor localized exposures before they escalate.

    B. Second-Line Risk Oversight and Independence

    The CRO leads the second line, maintaining independent authority to establish compliance standards, design evaluation methodologies, and challenge first-line operational assumptions. Maintaining direct access to the Board Risk Committee guarantees that risk oversight remains objective and uninfluenced by short-term revenue generation incentives.


    Financial charts and predictive risk modeling software on workstation screens
    Figure 2: Advanced risk analytics enable CROs to conduct forward-looking stress tests and dynamic capital allocation.

    3. Building a Quantitative Risk Appetite Statement (RAS)

    A qualitative understanding of risk is insufficient for modern board governance. Female risk executives must translate high-level board vision into quantifiable financial parameters. Establishing formal statements guided by standards from the Financial Stability Board (FSB) protects enterprise capital stability.

    • Capital Allocation Limits: Defining strict maximum acceptable loss caps (e.g., limiting potential downside impact of any single operational failure to under 2.5% of EBITDA).
    • Liquidity Stress Thresholds: Setting mandatory buffer ratios for operating cash flows to survive severe 90-day market liquidity shocks.
    • Cyber Resilience Standards: Codifying maximum allowable recovery time objectives (RTO) and recovery point objectives (RPO) across enterprise technology systems.

    4. Tactical Playbook: Implementing Executive Risk Governance

    Executing an enterprise-wide risk framework requires deliberate rollout, continuous board communication, and data integration. Follow this step-by-step executive protocol:

    Chief Risk Officer Implementation Protocol

    1. Map Strategic Objectives to Risk Taxonomy: Align top enterprise growth initiatives directly with quantified strategic, operational, and financial risk categories.
    2. Formalize Board Reporting Dashboards: Transition from static qualitative risk matrices to dynamic risk appetite heatmaps updated quarterly.
    3. Institute Rigorous Scenario Stress Testing: Run forward-looking simulations testing organizational resilience under macroeconomic downturns and severe cyber incidents.
    4. Embed Risk Metrics into Executive Compensation: Partner with compensation committees to tie executive bonuses to risk-adjusted return metrics.
    5. Deploy Continuous Monitoring Tools: Automate data aggregation across third-party vendor ecosystems and internal infrastructure.

    5. Related Strategic Leadership Guides

    Expand your executive knowledge base by exploring our complementary guides in the WomenSteps leadership series:

    6. Frequently Asked Questions

    What is the primary difference between COSO ERM and ISO 31000?

    COSO ERM focuses heavily on strategy, governance, internal controls, and financial compliance. ISO 31000 provides a flexible, principles-based framework that can be easily customized across operational processes in any industry.

    How does a Chief Risk Officer establish a quantitative Risk Appetite Statement?

    A CRO translates board performance objectives into measurable tolerance bands across key financial indicators (e.g., maximum acceptable capital loss percentage), liquidity reserves, operational uptime limits, and legal compliance thresholds.

    Why is stress testing critical for executive risk reporting?

    Stress testing evaluates how severe but plausible adverse events (such as market crashes or cyber breaches) impact corporate capital adequacy and strategic operations, providing the board with empirical evidence of organizational resilience.

    What is the Three Lines Model in enterprise risk governance?

    The Three Lines Model defines organizational risk roles: First-Line operational management owns and manages risk; Second-Line risk and compliance functions (led by the CRO) provide framework oversight; and Third-Line internal audit provides independent assurance.

    Conclusion: Leading Strategic Risk Governance in Modern Enterprises

    Enterprise risk management is no longer merely a defensive compliance check; it is a fundamental catalyst for sustainable corporate performance. By standardizing global ERM frameworks, establishing clear risk appetite boundaries, and delivering transparent risk reporting to the board, female Chief Risk Officers elevate risk management into a strategic advantage.

    As corporate environments face evolving geopolitical, financial, and technological disruptions, executive female leaders who master quantitative risk governance ensure their organizations remain resilient, compliant, and positioned for long-term growth.

  • D&O Insurance & Business Interruption for Female Founders

    D&O Insurance & Business Interruption for Female Founders


    Scaling a venture-backed enterprise or high-growth business requires balancing strategic aggressive expansion with enterprise risk mitigation. For women founders navigating funding rounds, board oversight, and complex commercial vendor networks, Directors and Officers (D&O) insurance and robust business interruption coverage form the ultimate safeguard for business survival and personal asset protection.

    While early-stage entrepreneurs often focus heavily on operational capitalization and product execution, corporate governance exposures can expose founders to personal liability from investors, regulators, employees, and competitors. Guidance provided by the U.S. Small Business Administration (SBA) emphasizes that comprehensive risk structuring is vital to long-term enterprise solvency. This guide outlines how female executives can structure corporate insurance policies, secure board indemnification, and safeguard revenue streams against unforeseen operational halts.

    Figure 1: Proactive risk governance aligns founder indemnification with institutional investor expectations.

    1. Deconstructing D&O Insurance Architecture: Side A, B, and C

    Directors and Officers liability coverage protects individual leadership teams against personal financial loss arising from lawsuits alleging wrongful management decisions, breach of fiduciary duty, or operational misstatements. Understanding the three primary coverage pillars is crucial when reviewing broker terms.

    Coverage Layer Target Insured Entity Operational Trigger Condition Personal Asset Exposure Risk
    Side A Coverage Individual Officers & Board Members Company is insolvent or legally unable to indemnify Direct personal asset protection (Zero Deductible)
    Side B Coverage The Corporate Entity (Indemnification) Company indemnifies directors for defense legal costs Reimburses balance sheet after corporate payout
    Side C Coverage The Corporate Entity (Direct) Direct entity claims (Public securities/shareholder litigation) Protects balance sheet assets from institutional claims

    2. Managing Fiduciary Liability and Corporate Governance Risks

    As female founders scale board structures and accept venture capital, governance scrutiny increases. According to legal standards curated by the Legal Information Institute at Cornell Law School, executive directors owe strict duties of care, loyalty, and good faith to shareholders.

    A. Venture Capital Board Dynamics and Misalignment

    Conflict frequently arises between early-stage equity holders, founder directors, and incoming institutional investors regarding milestone valuations, follow-on dilution, or M&A exits. D&O insurance funds independent legal defense in the event minority shareholders file breach of fiduciary duty lawsuits during down-rounds or recapitalizations.

    B. Regulatory Compliance and Employment Practices Liability (EPLI)

    Modern enterprise risk extends beyond financial accounting errors. Combining D&O coverage with Employment Practices Liability Insurance (EPLI) protects the management team against allegations of systemic workplace discrimination, wrongful termination, or executive retaliation.

    Figure 2: Comprehensive business interruption plans calculate payroll continuation, fixed expenses, and operational downtime mitigation.

    3. Business Interruption Insurance: Safeguarding Revenue Continuity

    While D&O protects management against liability claims, Business Interruption (BI) insurance protects the cash flow that keeps the business operational during unforeseen physical disasters or supply chain failures. Standard guidelines established by the National Association of Insurance Commissioners (NAIC) reinforce the importance of maintaining adequate indemnity periods.

    A. Core Components of Business Income Coverage

    • Net Income Restoration: Replaces operating net profits based on pre-disaster financial statements.
    • Fixed Expense Maintenance: Covers ongoing payroll commitments, debt obligations, lease obligations, and taxes during operational halts.
    • Extra Expense Provisions: Funds temporary office relocation, equipment leasing, and accelerated freight costs to maintain client service levels.

    B. Contingent Business Interruption (CBI) for Supply Chains

    Female founders running e-commerce, biotechnology, or hardware enterprises face severe upstream vulnerability. Contingent Business Interruption expands your policy to cover lost revenue when a key third-party vendor, manufacturer, or cloud hosting provider suffers physical damage or downtime.

    4. Critical Policy Exclusions & Retention Terms

    Understanding policy exclusions prevents catastrophic surprises during claim filings. Founders should work closely with brokers to negotiate standard carve-outs and retain management control over legal defense counsel selection.

    • Prior Acts Exclusion: Ensures policies cover actions taken prior to the inception date of the policy. Founders should demand full prior-acts coverage when migrating between carriers.
    • Insured vs. Insured Exclusion Carve-Outs: Standard policies exclude claims brought by one insured officer against another. Female founders must ensure exceptions exist for derivative suits, employment claims, or actions brought by non-executive directors.
    • Waiting Period Clauses in Business Interruption: Most business income policies carry a 24- to 72-hour waiting period deductible before payments trigger. Retaining emergency operational reserves bridges this initial financial gap.

    5. Tactical Risk Protocol for Founders During Mergers & Acquisitions

    When selling your enterprise or leading an exit, governance liability does not end at closing. Use this protocol to protect your post-sale liquidity:

    Female Founder M&A Insurance Protocol

    1. Secure 6-Year D&O Tail Insurance: Mandate that the acquiring company purchases (or funds from transaction proceeds) a 6-year “run-off” policy to cover acts committed prior to deal close.
    2. Utilize Representation & Warranty (R&W) Insurance: Transfer financial exposure for post-closing indemnity claims from the founder’s escrow account to an institutional insurer.
    3. Review Indemnification Carve-Outs: Ensure corporate charter agreements retain maximum allowable director exculpation protections under state law.
    4. Audit Cyber Interruption Riders: Validate that business interruption policies include specialized ransomware and cloud outage coverage extensions.

    6. Related Strategic Leadership Guides

    Build a fully comprehensive corporate strategy by exploring our existing leadership resources:

    7. Frequently Asked Questions

    When should a venture-backed female founder purchase D&O insurance?

    Founders should secure D&O coverage prior to closing seed or Series A investment rounds. Venture capital firms almost universally require D&O insurance as a mandatory closing condition before taking seats on your board of directors.

    Does business interruption insurance cover supply chain disruption?

    Standard policies only cover direct physical damage to your primary facility. To protect against key supplier or vendor downtime, founders must specifically purchase Contingent Business Interruption (CBI) coverage.

    What is D&O tail coverage and why is it necessary during an acquisition?

    Tail coverage extends a claims-made D&O policy for a set period (typically 6 years) post-sale. It protects founders from late-emerging lawsuits filed by shareholders or buyers after the company is acquired or dissolved.

    What is Side A D&O insurance coverage?

    Side A coverage directly indemnifies individual directors and officers when the corporate entity is unable or legally barred from doing so, such as during corporate bankruptcy or insolvency proceedings.

    Conclusion: Building Governance Resilience in Female-Led Enterprises

    Securing comprehensive D&O and business interruption coverage is not merely a legal obligation; it is a fundamental growth strategy. By protecting personal balance sheets, establishing clear board indemnification terms, and hedging against revenue disruption, female founders create resilient corporate structures built to withstand scaling pressure and market volatility.

    Proactively managing governance exposure allows female executives to lead with authority, negotiate from strength with institutional investors, and execute long-term enterprise goals with complete peace of mind.

  • Executive Compensation Negotiation for Women: RSUs, Equity, and Severance Strategies

    Executive Compensation Negotiation for Women: RSUs, Equity, and Severance Strategies


    As female corporate leaders ascend to Vice President, Senior Vice President, and C-suite positions, navigating executive compensation negotiation shifts from discussing base salary to structuring complex, multi-tiered total financial packages. Enterprise compensation structures at senior levels are designed around long-term value creation, performance-contingent incentives, and risk-mitigation covenants. For women executives, mastering the mechanics of Restricted Stock Units (RSUs), stock options, performance bonuses, and double-trigger severance terms is essential to securing earnings equity and long-term financial independence.

    Despite increased representation in senior leadership, research published in the Harvard Business Review highlights that female executives frequently face widening compensation gaps at the equity level rather than base pay. Bridging this gap requires an analytical, data-driven approach to total reward valuation. This comprehensive guide breaks down the core components of executive compensation, offering tactical frameworks for negotiating equity grants, vesting acceleration, clawback protections, and executive exit provisions.

    Figure 1: Strategic compensation negotiation aligns executive performance with equity and long-term enterprise value.

    1. Deconstructing the C-Suite Total Rewards Architecture

    At the executive level, base salary typically accounts for less than 30% to 40% of total annual target compensation. The remainder is distributed across short-term incentives, long-term equity vehicles, and deferred compensation plans. Understanding how board compensation committees construct these tiers provides the leverage needed during negotiations.

    Compensation Component Primary Structure Risk & Liquidity Profile Strategic Negotiation Objective
    Base Salary Guaranteed cash compensation Immediate liquidity / Zero risk Establish baseline for multiplier calculations (severance, STI)
    Short-Term Incentives (STI) Annual performance bonus based on KPIs Annual liquidity / Moderate performance risk Define objective metric thresholds and pro-rata exit guarantees
    Restricted Stock Units (RSUs) Time-based stock grants Medium-term liquidity / Market price volatility risk Shorten cliff schedules and negotiate double-trigger vesting
    Performance Stock Units (PSUs) Tied to corporate goals (EBITDA, TSR) Delayed liquidity / High corporate execution risk Ensure realistic target benchmarks and catch-up provisions
    Severance Covenants Contractual payout on involuntary termination Conditional liquidity / Downside risk insurance Secure 12–24 months base + bonus cash continuation

    2. Mastering Long-Term Incentive Plans (LTIPs): RSUs vs. Stock Options

    Long-term incentives serve as the main driver of net-worth expansion for senior corporate executives. However, accepting equity without scrutinizing grant mechanics, tax implications, and dilution protocols can result in substantial lost value.

    A. Restricted Stock Units (RSUs) and Performance Shares (PSUs)

    RSUs represent a commitment to deliver company shares upon meeting specific vesting schedules. Unlike stock options, RSUs maintain intrinsic value regardless of market dips, provided the enterprise remains solvent.

    • Vesting Schedule Optimization: The standard corporate vest follows a 4-year schedule with a 1-year cliff (25% vesting at month 12, followed by monthly or quarterly vesting). Female leaders entering high-growth or volatile sectors should negotiate monthly vesting post-cliff or a 3-year compressed vesting cycle.
    • Performance-Based PSUs: When granted PSUs, evaluate whether performance metrics are tied to Total Shareholder Return (TSR) relative to peer indices or internal operating targets (such as EBITDA margins or revenue growth). Ensure that peer groups are explicitly named in the compensation contract to prevent goalpost shifting.

    B. Non-Qualified Stock Options (NSOs) vs. Incentive Stock Options (ISOs)

    In high-growth tech and venture-backed private companies, stock options remain a cornerstone of executive offers. Executives must distinguish between option structures:

    • Incentive Stock Options (ISOs): Provide favorable capital gains tax treatment if held for required statutory periods, but are subject to strict annual $100,000 grant caps under federal regulations detailed by the Internal Revenue Service (IRS).
    • Non-Qualified Stock Options (NSOs): Taxed as ordinary income upon exercise based on the spread between strike price and fair market value. Negotiate extended Post-Termination Exercise Windows (PTEW)—expanding the standard 90-day exercise period to 3–7 years upon departure—to prevent losing vested options due to short-term illiquidity.

    3. Executive Severance Agreements and Change-of-Control Provisions

    A compensation negotiation is incomplete without structuring downside protection. Executive severance agreements, often termed “golden parachutes,” safeguard leaders against corporate restructuring, M&A activity, and board governance shifts.

    Stock market charts and financial equity analysis on modern display
    Figure 2: Structuring double-trigger vesting and robust severance terms protects executive equity during corporate mergers and acquisitions.

    A. Defining Involuntary Termination and “Good Reason” Resignation

    Severance packages trigger upon termination without “Cause.” However, high-performing female executives must also negotiate robust “Good Reason” departure clauses. A Good Reason clause permits the executive to resign while retaining full severance benefits under conditions such as:

    • A material reduction in base compensation or target bonus opportunity.
    • A significant demotion in title, reporting line (e.g., no longer reporting directly to the CEO or Board), or core operational responsibilities.
    • Mandatory geographic relocation exceeding 30 to 50 miles from the primary corporate office.

    B. Double-Trigger vs. Single-Trigger Change-of-Control Clauses

    During corporate mergers, acquisitions, or private equity buyouts, executive equity is vulnerable. Female leaders should negotiate double-trigger change-of-control provisions:

    • Trigger 1: The execution of a corporate acquisition or change in majority ownership control.
    • Trigger 2: Involuntary termination or resignation for “Good Reason” within 12 to 24 months following the transaction.
    • Result: Upon activation of the second trigger, 100% of unvested RSUs, stock options, and long-term cash bonuses accelerate and vest immediately.

    4. Tactical Framework: Step-by-Step Negotiation Playbook for Women

    Successfully executing an executive compensation negotiation requires careful positioning, market benchmarking, and timing. Utilize this tactical framework during discussions with board compensation committees:

    Executive Compensation Negotiation Protocol

    1. Conduct Independent Peer Group Benchmarking: Utilize public disclosures such as SEC Form DEF 14A proxy statements on the SEC EDGAR Database to evaluate market compensation tiers for comparable roles.
    2. Separate Base Discussions from Total Target Opportunity: Secure base compensation first before negotiating STI multipliers, equity grant value, and clawback exemptions.
    3. Quantify Unvested Equity Forfeiture (“Make-Whole” Grants): When transitioning from a previous employer, demand a sign-on cash bonus or immediate RSU grant to offset unvested equity left behind.
    4. Negotiate Executive Legal Fee Coverage: Request corporate reimbursement (typically $5,000–$15,000) for independent executive legal counsel to review employment contracts prior to signature.
    5. Secure Non-Financial Corporate Commitments: Include contractual provisions for dedicated executive coaching, administrative resources, and board-seat participation approvals.

    5. Related Strategic Leadership Guides

    To continue building your leadership authority and operational impact across corporate environments, explore our strategic executive guides:

    6. Frequently Asked Questions

    What is the standard RSU vesting schedule for C-suite executives?

    The corporate baseline follows a 4-year vesting schedule with a 1-year cliff (25% vesting at month 12, followed by monthly or quarterly vesting). Female executives can negotiate compressed 3-year vesting timelines or monthly post-cliff vesting cycles.

    What is a double-trigger change-of-control clause?

    A double-trigger clause requires two distinct events to occur before unvested equity accelerates: first, a corporate acquisition or merger occurs, and second, the executive is terminated without Cause or resigns for ‘Good Reason’ within 12 to 24 months post-deal.

    How do female executives negotiate legal fee coverage for contracts?

    Executives can request a dedicated legal reimbursement covenant (typically $5,000 to $15,000) included in their term sheet to retain independent executive compensation attorneys to review agreements prior to execution.

    What qualifies as a “Good Reason” resignation in executive severance?

    A Good Reason clause allows an executive to resign while keeping full severance benefits. Common triggers include a reduction in base salary or bonus potential, a major demotion in title or reporting line, or a forced office relocation over 30 to 50 miles.

    Conclusion: Securing Financial Equity in Senior Leadership

    Negotiating an enterprise executive compensation package is fundamentally an exercise in risk management and value alignment. By mastering equity grant mechanics, securing acceleration covenants, and structuring protective severance terms, female corporate leaders ensure that their financial compensation directly reflects their operational impact and enterprise value creation.

    As organizations continue to rely on high-performing female leadership to navigate complex market conditions, approaching compensation negotiations with empirical data, clear legal protections, and long-term equity goals ensures sustained financial success throughout your executive career.

  • Executive Coaching for Women Leaders: ROI, Frameworks, and C-Suite Strategy

    As enterprise operational environments face compounding complexity—driven by rapid artificial intelligence adoption, macroeconomic volatility, evolving corporate governance, and shifting international supply chains—the strategic implementation of executive coaching for women leaders has transitioned from an optional career enrichment perk into a core corporate imperative. Organizations targeting sustained profitability and robust succession pipelines prioritize female leadership density across the C-suite, leveraging empirical executive development frameworks to align cross-functional strategy, reduce top-tier executive churn, and maximize shareholder value.

    However, navigating the upper echelons of corporate governance requires specialized skill sets that traditional management training rarely addresses. Female leaders frequently operate within complex matrix organizations, balancing high-stakes decision-making with distinct systemic expectations. This comprehensive blueprint analyzes the financial, behavioral, and operational frameworks underlying executive coaching, establishing how female corporate leaders can utilize targeted coaching interventions to master enterprise negotiations, optimize executive presence, and secure board-level seats.

    Female corporate executive leading strategic enterprise planning in boardroom
    Figure 1: Executive coaching arms women leaders with data-backed frameworks to command authority during complex enterprise turnarounds.

    1. The Business Case: Financial ROI, Metrics, and Enterprise Performance

    Professional executive coaching operates on systematic, outcome-oriented methodologies grounded in organizational psychology and financial analysis. Unlike informal internal mentorship or general career advice, certified coaching employs structured diagnostic evaluations, qualitative 360-degree feedback loops, and strict key performance indicators (KPIs) tied directly to profit-and-loss (P&L) performance.

    Comprehensive empirical research published by the International Coaching Federation (ICF) reveals that enterprise investment in executive coaching yields an average Return on Investment (ROI) of 5.7 times the initial cost—exceeding 500% financial returns. Organizations report significant gains in operational output, accelerated product delivery timelines, and substantial reductions in senior leadership turnover costs, which often run between 150% and 200% of an executive’s annual base salary.

    Furthermore, analytical studies featured in the Harvard Business Review highlight that structured executive coaching shifts a leader’s orientation from operational execution to strategic vision. Female executives paired with certified coaches demonstrate higher success rates when steering cross-border mergers and acquisitions (M&A), executing digital infrastructure transformations, and managing investor relations during public earnings updates.

    Strategic Dimension Internal Mentorship Sponsorship Initiatives Certified Executive Coaching
    Core Focus Knowledge transfer & advice Internal networking & promotion advocacy Systemic operational performance & leadership psychology
    Methodology Informal, situational conversations Executive placement backing Psychometrics, 360-degree audits, diagnostic KPIs
    Objectivity Level Low (internal company bias) Low (bound by internal politics) High (third-party neutral accountability)
    Accountability Structure Voluntary check-ins Event-driven alignment Formal contract, baseline development milestones
    Measurable Financial Impact Incremental career advancement Increased promotion probability Accelerated C-suite placement & documented enterprise ROI

    2. Overcoming Systemic Friction Points in Female Leadership

    While executive capabilities are universal, the corporate landscape presents specific structural dynamics that female leaders must navigate. Executive coaching directly targets these systemic friction points, replacing defensive tactics with offensive strategic leadership frameworks.

    A. The Communication Paradox (The “Double-Bind” Dilemma)

    Social science research consistently identifies the communication double-bind affecting female executives: women who exhibit highly decisive, authoritative leadership styles risk being labeled as overly aggressive, while those who adopt warm, collaborative styles risk having their executive authority questioned. Executive coaches work with female leaders to establish an authentic communication strategy using frame control techniques, calibrated tone modulation, and non-verbal presence to project unquestioned authority while maintaining high emotional intelligence.

    B. Hyper-Visibility vs. Hyper-Invisibility

    Female leaders in male-dominated industries (such as Technology, Private Equity, Investment Banking, and Industrial Manufacturing) often experience an exhausting paradox. They face intense hyper-visibility regarding their mistakes or personal style, yet suffer hyper-invisibility regarding their strategic contributions and P&L achievements. Coaching engagements construct systematic self-advocacy models, ensuring that business results are clearly attributed to the leader’s strategic direction during board reviews and executive evaluations.

    C. Breaking the “Over-Mentored, Under-Sponsored” Trap

    Corporate audits indicate that while women are frequently enrolled in internal mentorship programs, they receive far less active strategic sponsorship than their male counterparts. Mentors give advice; sponsors utilize their political capital to advocate for candidates behind closed doors during C-suite succession meetings. Executive coaching transforms how female leaders build corporate alliances, teaching them how to convert passive mentors into active executive sponsors who advocate for their appointment to high-leverage positions.

    3. Core Pillars of Strategic Executive Coaching for Women

    Targeted executive development focuses on high-leverage competencies that drive enterprise expansion and career longevity:

    Executive metrics graph displaying organizational performance growth
    Figure 2: Executive coaching establishes quantitative milestones to measure executive growth alongside financial business outputs.

    A. Advanced C-Suite Negotiation & Total Compensation Structuring

    Executive compensation at senior director, VP, and C-suite levels differs radically from mid-management salaries. Total compensation package structures require sophisticated negotiation to align short-term cash flow with long-term wealth creation. Executive coaches assist female leaders in negotiating robust equity packages, clawback protection, and performance thresholds:

    • Base Compensation & Variable Short-Term Incentives (STI): Structuring quarterly and annual bonus triggers around measurable operational metrics rather than subjective performance reviews.
    • Long-Term Incentives (LTI) & Equity Grants: Navigating Restricted Stock Units (RSUs), Non-Qualified Stock Options (NSOs), and Incentive Stock Options (ISOs). Executive coaches evaluate vesting schedules, cliff periods, and performance-contingent stock units (PSUs) to ensure equity aligns with company valuation targets.
    • Golden Parachutes & Change-of-Control Provisions: Negotiating robust severance covenants, including double-trigger change-of-control clauses that protect executive payouts, equity acceleration, and health benefits during corporate M&A transactions or activist investor takeovers.
    • Board Seat Authorization: Securing contract provisions that explicitly allow the executive to serve on outside corporate or advisory boards, accelerating their broader industry influence.

    B. Psychometric Diagnostics & Leadership Psychology

    High-performance executive coaching relies on validated behavioral diagnostics to uncover operational blind spots, stress reactions, and interpersonal style variations. Leading coaches utilize top-tier psychological frameworks, including:

    • Hogan Assessments Suite: Utilizing the Hogan Personality Inventory (HPI) for day-to-day strengths, the Hogan Development Survey (HDS) to identify behavioral derailers under intense corporate stress, and the Motives, Values, Preferences Inventory (MVPI) to determine core cultural alignment.
    • The Birkman Method: Analyzing underlying needs, occupational interests, and potential stress behaviors to optimize interpersonal team dynamics within executive cabinets.
    • Qualitative 360-Degree Executive Audits: Conducting confidential, structured interviews with board members, direct reports, lateral peers, and key clients to build an objective map of perceived executive authority and operational efficiency.

    C. Strategic Boardroom Influence & Media Relations

    Ascending to top corporate roles requires mastering high-stakes stakeholder management. Executive coaching builds communication capabilities tailored for boardrooms, investor presentations, and national media appearances. Coaches help leaders refine their message architecture, handle aggressive shareholder questioning, and maintain poise during corporate crises or operational disruptions.

    4. Case Studies: Real-World Enterprise Impact

    Examining real corporate scenarios demonstrates how executive coaching transforms operational performance and career trajectories:

    Case Study 1: Transforming a Senior VP into Chief Operating Officer (Enterprise Tech)

    The Challenge: A Senior VP of Engineering at a US-based SaaS enterprise was consistently passed over for the COO position despite delivering exceptional platform uptime and engineering output. Internal feedback cited a perceived lack of “commercial presence” and “strategic financial vision.”

    The Intervention: The executive engaged an ICF-certified Master Executive Coach for a 9-month program. The coach focused on shifting her communication from technical execution to enterprise financial metrics, mastering P&L management narratives, and conducting mock board presentations.

    The Outcome: Within 7 months, the executive successfully presented a multi-year cloud architecture strategy directly to the Board of Directors. When the COO position opened, she was unanimously appointed, negotiating a 45% increase in overall compensation, including performance-contingent equity grants.

    Case Study 2: Managing Post-Merger Operational Integration (Healthcare Sector)

    The Challenge: Following a $1.2B healthcare acquisition, a female Managing Director faced severe cultural friction, cross-team resistance, and key talent attrition within her newly integrated division.

    The Intervention: Through targeted coaching, the MD utilized 360-degree feedback tools and stakeholders mapping to realign divisional leadership. The coach helped her implement structured change-management communication protocols and transparent accountability measures.

    The Outcome: Voluntary turnover dropped by 62% over 12 months, divisional operational integration was completed two quarters ahead of schedule, and the MD received the company’s internal Leadership Excellence Award.

    5. The Step-by-Step Selection Playbook: How to Choose the Right Coach

    Partnering with the wrong coach leads to wasted financial investment and misaligned development strategies. Organizations and individuals should follow this multi-stage selection framework:

    Executive Coach Rigorous Vetting Framework

    1. Verify Top-Tier Credentials: Confirm credentials from global governing bodies. Look for ICF Professional Certified Coach (PCC) or Master Certified Coach (MCC) designations, or credentials from the European Mentoring and Coaching Council (EMCC).
    2. Evaluate Industry & Corporate Context: Ensure the coach possesses direct experience advising leaders in high-stakes environment (e.g., Fortune 500, VC-backed tech growth, heavily regulated sectors).
    3. Audit Diagnostic Methodology: Confirm the coach utilizes validated psychometric tools (Hogan, Birkman, Leadership Circle Profile) rather than unverified questionnaires.
    4. Define Pre-Engagement Benchmarks: Establish baseline KPIs prior to contract execution. Ensure clear evaluation check-ins at 30, 60, and 90 days.
    5. Test Chemistry and Challenge Dynamics: The ideal coach is not a cheerleader; they must serve as a trusted, challenging sparring partner capable of delivering constructive, unfiltered feedback.

    6. Budgeting, Corporate Funding, and Tax Considerations

    Navigating the financial execution of an executive coaching engagement involves understanding corporate budget allocation structures and potential tax implications:

    A. Securing Corporate Sponsorship and L&D Budgets

    Most enterprise organizations maintain dedicated Learning & Development (L&D), Executive Talent Development, or Succession Planning budgets to fund executive coaching. When requesting corporate sponsorship, female leaders should frame the proposal around business outcomes (e.g., operational efficiency, P&L expansion, key talent retention) rather than personal development.

    B. Out-of-Pocket Investment & Tax Deductibility (US Focus)

    When executives fund coaching independently to maintain complete confidentiality from their current employer, costs can range from $5,000 to $25,000+ for standard 6-to-12-month engagements. In the United States, self-funded coaching that directly maintains or improves skills required in an executive’s current trade or business may qualify as an allowable professional expense, depending on current IRS guidelines and individual tax structuring. Executives should consult a certified CPA to evaluate tax-deductibility avenues within their specific corporate structure.

    Conclusion: Securing Strategic Command in Modern Business

    As corporate structures adapt to rapid global changes, the role of executive coaching for women leaders stands as a key catalyst for sustained organizational achievement. By replacing fragmented advice with evidence-based behavioral psychology, sophisticated negotiation strategies, and validated leadership metrics, executive coaching gives women the tools to lead corporate turnarounds, maximize enterprise performance, and command long-term influence in executive boardrooms nationwide.

    For ambitious female leaders and forward-thinking corporations alike, investing in professional executive coaching is not simply an expenditure—it is a high-yield strategic investment that drives executive excellence and long-term organizational success.

  • Affordable Health Insurance in Georgia: How to Find Plans Under $300

    Affordable Health Insurance in Georgia: How to Find Plans Under $300

    Disclaimer:
    This article is for informational and educational purposes only and does not constitute financial, legal, insurance, or healthcare advice. Health insurance eligibility, premiums, deductibles, and tax credits vary by household income, age, county, and family size. Always verify your eligibility and plan details through official state resources or a licensed professional.

    Finding health insurance in Georgia for under $300 per month is achievable for many individuals and families, particularly when leveraging federal subsidies through Georgia Access. However, because final premiums depend heavily on household size, age, income, and zip code, navigating your options requires looking past advertised base rates to calculate your true out-of-pocket costs.

    Georgia residents shop for individual and family coverage through Georgia Access, the state’s official health insurance marketplace. Depending on your financial profile, you may qualify for Advance Premium Tax Credits (APTC) or Cost-Sharing Reductions (CSR). Additionally, state-specific programs like Georgia Pathways to Coverage™ and PeachCare for Kids® offer alternative avenues for qualifying households.

    Guide to finding affordable health insurance plans under $300 in Georgia through Georgia Access
    A practical guide to comparing Georgia health insurance, financial assistance, and public coverage options.

    Understanding Georgia Access: Georgia’s Health Marketplace

    Georgia Access serves as the state-based marketplace where residents compare Qualified Health Plans (QHPs), determine subsidy eligibility, and enroll. While private web brokers and agents partner with the state, official plan pricing and subsidy calculations remain standardized across all channels.

    A primary misconception is that a “$300 plan” is a static tier. In reality, $300 is a net calculation after applying subsidies to full-price benchmark plans in your specific county.

    What Marketplace Health Plans Cover

    All ACA-compliant Qualified Health Plans cover ten federal Essential Health Benefits, ensuring foundational care regardless of the plan’s monthly cost:

    • Ambulatory Care: Outpatient medical care without hospital admission.
    • Emergency Services: Urgent medical treatment without pre-authorization requirements.
    • Hospitalization: Inpatient surgical and medical care.
    • Maternity & Newborn Care: Pregnancy, prenatal, and postnatal care.
    • Mental Health & Substance Use Treatment: Behavioral health and therapy services.
    • Prescription Drugs: Formulated medication access categorized by drug tiers.
    • Preventive & Wellness Services: Annual physicals and screenings covered at $0 out-of-pocket when in-network.
    • Pediatric Services: Comprehensive pediatric dental, vision, and health benefits.

    Understanding Your Monthly Premium

    How a Plan Falls Below $300

    Your net premium reflects sticker price minus your estimated tax credit.

    💳

    Gross Premium
    Full plan cost

    −
    💰

    Tax Credit (APTC)
    Based on household income

    =
    ✓

    Net Out-of-Pocket
    Target: Sub-$300/mo

    How Premium Tax Credits Reduce Monthly Costs

    Subsidies are calculated against Federal Poverty Guidelines (FPL). Your household income as a percentage of FPL determines how much you are expected to contribute toward health coverage, with the tax credit filling the gap.

    Federal Poverty Guidelines Reference

    Household Size 100% FPL 200% FPL 400% FPL
    1 person $15,960 $31,920 $63,840
    2 people $21,640 $43,280 $86,560
    3 people $27,320 $54,640 $109,280
    4 people $33,000 $66,000 $132,000

    Real-World Scenario: The Sub-$300 Math in Action

    Profile: Sarah, a 34-year-old self-employed graphic designer living in Fulton County, GA.

    • Projected Annual Income: $32,000 (~200% FPL for a single household)
    • Unsubsidized Benchmark Silver Plan Premium: $460/month
    • Calculated Advance Premium Tax Credit (APTC): $215/month
    • Sarah’s Net Monthly Cost (Silver Plan): $245/month

    Outcome: Because Sarah chose a Silver tier plan while earning under 250% FPL, she not only reduced her premium below $300 ($245/mo), but also unlocked Cost-Sharing Reductions (CSR) that lowered her annual deductible from $5,500 down to $1,200.

    Comparing ACA Metal Tiers in Georgia

    Plans on Georgia Access fall into four distinct metal categories based on actuarial split—how costs are shared between you and the insurer.

    ACA Metal Tiers Overview

    🥉

    Bronze

    Lowest premiums
    Highest deductible care

    🥈

    Silver

    Moderate premiums
    Best value via CSR

    🥇

    Gold

    Higher premiums
    Lower medical copays

    💎

    Platinum

    Highest premiums
    Lowest deductible care

    Metal Tier Actuarial Split Cost Profile Recommended For
    Bronze 60% / 40% Lowest premium / high out-of-pocket Healthy individuals seeking emergency financial protection.
    Silver 70% / 30% Balanced premium / moderate out-of-pocket Anyone qualifying for Cost-Sharing Reductions (CSR).
    Gold 80% / 20% Higher premium / low out-of-pocket Individuals managing chronic illness or frequent prescriptions.

    Key Insurance Carriers in Georgia

    Carrier participation varies significantly by county. Major insurers offering coverage through Georgia Access include:

    • Ambetter (Peach State Health Plan): Broad statewide presence with competitive Bronze and Silver pricing.
    • Anthem Blue Cross and Blue Shield: Extensive regional doctor and hospital network.
    • Kaiser Permanente: Integrated HMO care model active primarily in Metro Atlanta regions.
    • Oscar Health: Technology-focused user experience with virtual urgent care integrations.
    • Alliant Health Plans: Regional carrier serving many northern and rural Georgia counties.

    Specialized Public Coverage Programs

    Georgia Pathways to Coverage™

    Designed for low-income adults ages 19–64 earning up to 100% FPL who do not qualify for traditional Medicaid. Beneficiaries must complete at least 80 hours per month of qualifying activities (work, job training, or community service) to retain coverage.

    PeachCare for Kids®

    Provides comprehensive healthcare coverage for uninsured children under age 19 in families earning up to 247% FPL. Services include dental, vision, preventive doctor visits, and hospital care at low or zero cost.

    Georgia Access Comparison Checklist

    ✓ Net Premium

    Your actual cost after tax credit calculation.

    ✓ Annual Deductible

    Amount paid out-of-pocket before insurance kicks in.

    ✓ Network Type (HMO vs EPO)

    Verify your specific primary doctors and hospital networks.

    ✓ Drug Formulary Tier

    Confirm your current prescriptions are covered.

    When and How to Apply

    Annual Open Enrollment through Georgia Access runs from November 1 to January 15. Outside of Open Enrollment, you can enroll by qualifying for a Special Enrollment Period (SEP) through life events such as:

    • Loss of minimum essential coverage (job change or loss)
    • Marriage, divorce, or household addition (birth/adoption)
    • Permanent move to a new county in Georgia
    • Income change altering subsidy eligibility status

    Frequently Asked Questions

    Can I really get health insurance in Georgia under $300/month?

    Yes. Many single applicants earning between $22,000 and $40,000 qualify for APTC tax credits that drop their out-of-pocket Silver or Bronze plan premium below $300 per month.

    Is a Bronze plan better than a Silver plan if it is cheaper?

    Not always. If you qualify for Cost-Sharing Reductions (CSR) based on income, a Silver plan offers drastically reduced deductibles and copays, which often offsets a slightly higher monthly premium.

    How do I verify if my doctor takes a Georgia Access plan?

    Do not rely solely on carrier names. Use the exact plan network name (e.g., “Ambetter Guide” or “Anthem Pathway Guided Care”) when searching your doctor’s directory or contacting their billing office directly.

    Next Steps to Finalize Coverage

    Before submitting your final enrollment:

    • Verify your income projections match your tax filings
    • Confirm doctor and hospital network participation
    • Review drug formularies for required maintenance medications